By Musisi Lwanga
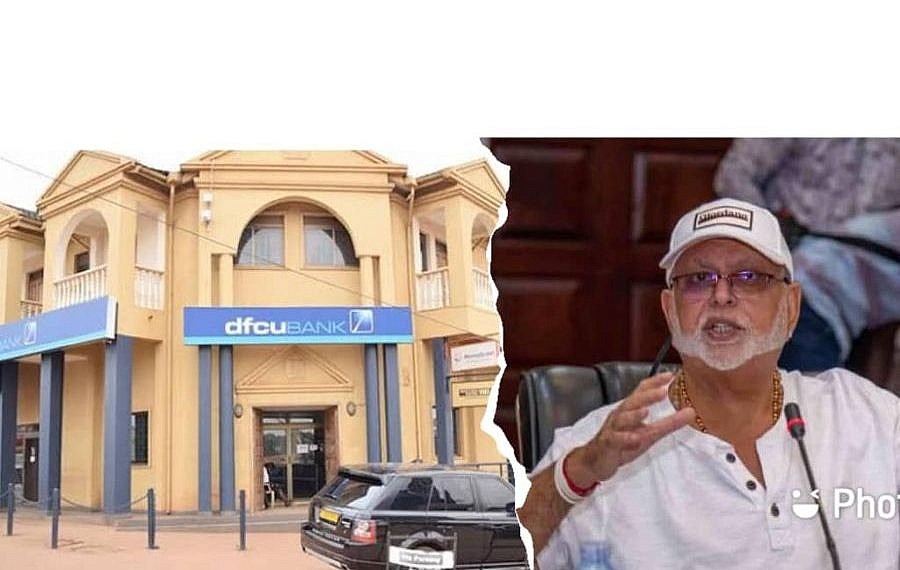
The high-stakes legal battle between Crane Bank, its former proprietor Sudhir Ruparelia and other shareholders, on one side, and DFCU Bank, its parent company, former and current directors and shareholders, on the other, has entered its second week at the High Court in London.
The 16-week trial centres on allegations by Crane Bank that DFCU Bank conspired with the Bank of Uganda (BoU) to facilitate the takeover of Crane Bank in January 2017 through what the claimants describe as unlawful means.
The proceedings have attracted public interest because of their potential implications for Uganda’s banking sector and the circumstances surrounding the transfer of Crane Bank’s assets and liabilities to DFCU Bank.
The case is being heard in London partly because of the corporate structures and foreign incorporation of some of the companies involved in the dispute.
However, the allegations remain before the court, and the final determination will depend on the evidence and legal arguments presented by the parties.
How the Crane Bank crisis unfolded
Between 2014 and 2016, the Bank of Uganda conducted on-site examinations and inspections of Crane Bank to assess its financial position.
According to the account presented in the proceedings, the central bank identified concerns relating to undercapitalisation, liquidity deficiencies, non-performing loans allegedly associated with inadequately monitored insider lending, and weaknesses in the bank’s corporate governance structures.
In August 2016, Crane Bank and the Bank of Uganda entered into a memorandum of understanding under which the commercial bank was expected to inject additional capital to improve its financial position.
By October 2016, Crane Bank had reportedly sought capitalisation support of approximately Shs115 billion from the central bank.
The Bank of Uganda declined the request and, on October 20, 2016, placed Crane Bank under statutory management.
The intervention was undertaken under Sections 82 to 88 of the Financial Institutions Act, which provides the legal framework for the regulation and supervision of financial institutions in Uganda.
Following the intervention, the process of identifying a potential buyer for Crane Bank’s assets and liabilities began.
DFCU Bank submitted its bid on December 20, 2016, and subsequently entered into a Purchase of Assets and Assumption of Liabilities Agreement with the Bank of Uganda in January 2017.

The agreement formed the basis of the transfer of Crane Bank’s assets and liabilities to DFCU Bank.
Why Crane Bank is suing DFCU
Crane Bank’s case centres on allegations that the process leading to the takeover was tainted by an unlawful scheme involving the Bank of Uganda.
According to the claims outlined in the proceedings, Crane Bank alleges that after the institution was placed under statutory management and subsequently receivership, the central bank pursued a transaction intended to transfer the bank to a Chinese investor, identified in the allegations as China Energy Company Limited (CEFC).
The claimants allege that when the proposed transaction involving the Chinese investor failed, DFCU Bank became the party through which the takeover was eventually carried out.
Crane Bank further alleges that DFCU Bank conspired with the Bank of Uganda through unlawful means, resulting in losses to Crane Bank in connection with the Purchase of Assets and Assumption of Liabilities Agreement.
These allegations have yet to be determined by the court. DFCU Bank’s liability, if any, will depend on the evidence and the court’s findings.
DFCU’s alleged involvement under scrutiny
One of the central questions in the trial is whether DFCU Bank was involved in any alleged scheme before Crane Bank was placed under statutory management on October 20, 2016.
The account of the proceedings presented so far indicates that DFCU Bank’s involvement in the transaction began after the central bank had intervened in Crane Bank.
This chronology is significant because the claimants must establish the alleged unlawful conduct and demonstrate how DFCU Bank was connected to the actions that allegedly caused them loss.
The timing of DFCU Bank’s entry into the transaction, however, does not by itself determine whether the allegations are true or false. The court will have to assess the documentary evidence, witness testimony and applicable law.
The Bank of Uganda’s absence from the case
Another significant issue is the absence of the Bank of Uganda as a party to the London proceedings, despite its central role in the events under dispute.
The explanation advanced in the discussion of the case is that the Foreign Act of State Doctrine may present a legal obstacle to examining certain acts performed by a foreign state’s authorities in the exercise of their sovereign powers.
The doctrine generally concerns limits on a foreign court’s ability to question the validity of certain acts of another sovereign state carried out within its own territory.
Its precise application depends on the circumstances and the law governing the proceedings. It should therefore not be assumed, without a specific ruling, that the doctrine automatically prevents every inquiry into the Bank of Uganda’s conduct.
The issue is important to Crane Bank’s claims because the alleged scheme places the central bank’s actions at the centre of the dispute.
With the regulator not directly represented as a defendant, the claimants face the task of establishing their allegations against the parties before the court while addressing the legal limits that may apply to evidence concerning the central bank’s actions.
Witnesses expected over the coming weeks
The trial is expected to continue for several more weeks, with testimony from witnesses representing DFCU Bank, its parent company and associated shareholders.
The proceedings are expected to include 19 witnesses from the DFCU side, including former and current directors, as well as expert witnesses.
The experts are expected to address issues relating to central banking practices, accountancy, valuation and the relevant Ugandan law.
Their testimony, together with documentary evidence and cross-examination, is expected to help the court assess the circumstances surrounding the transaction and the competing claims made by the parties.
As the 16-week trial continues, attention will remain on the evidence presented, the legal arguments over the Bank of Uganda’s role and whether Crane Bank can establish its allegations against DFCU Bank and the other defendants.
The proceedings remain ongoing, and no conclusion should be drawn about the merits of the claims until the court has determined the issues before it.
